Understanding Tax-Advantaged Accounts: 401(k), IRA, and HSA Explained
⚠️ Admin-only note — delete this box before publishing.
| Marker | Alt (EN) | Alt (KR) | Gemini Image Prompt |
|---|---|---|---|
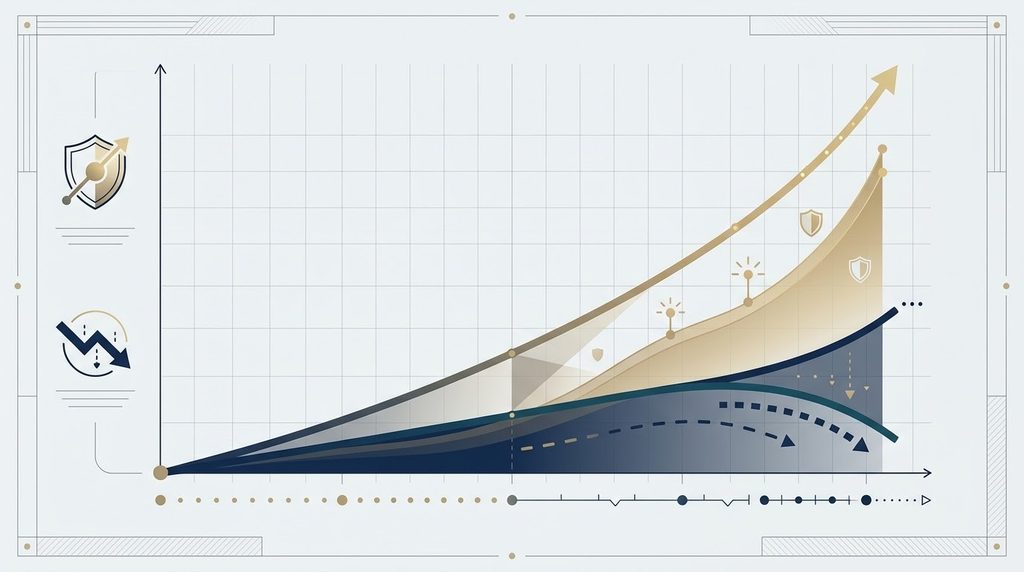
| IMAGE-1 | Diagram showing tax drag vs tax-free compound growth over 30 years | 30년간의 세금 차감 효과와 비과세 복리 성장을 비교한 다이어그램 | An elegant, clean financial infographic illustrating tax drag versus tax-advantaged compound growth over a 30-year horizon, modern corporate editorial style, soft navy blue and muted gold vector accents, no text or words |
| IMAGE-2 | Flowchart illustrating the optimal financial waterfall funding sequence across retirement accounts | 은퇴 계좌 간 최적의 자금 배분 순서를 보여주는 흐름도 | A clean financial waterfall flowchart diagram showing asset allocation hierarchy starting from employer match to HSA and IRA, subtle dark blue and teal design, minimalist modern aesthetic, crisp vector graphic, no text or words |
Featured Image
Prompt: A modern, sophisticated conceptual image representing financial balance and tax efficiency, showing three stylized shield pillars holding up growing balance scales, warm lighting, deep navy and rich emerald accents, modern editorial style, high resolution, 16:9 aspect ratio, no text or words
Alt (EN): Conceptual representation of tax-advantaged investment pillars including 401k, IRA, and HSA
Alt (KR): 401k, IRA, HSA를 포함한 절세 투자 기둥의 개념적 이미지
Description: A 16:9 editorial illustration symbolizing tax-advantaged financial architecture. / 절세 금융 구조를 상징하는 16:9 에디토리얼 일러스트레이션.
Introduction: The Hidden Engine of Compound Growth
Building long-term wealth is rarely determined by investment returns alone.
Tax efficiency plays an equally decisive role in determining your final net worth.
Every dollar lost to annual dividends, capital gains taxes, or income taxes is a dollar that can no longer compound.
Over three decades, tax drag can quietly reduce total wealth accumulation by thirty to forty percent.
Tax-advantaged accounts exist to eliminate or defer these friction points.
The U.S. tax code provides specific structures designed to encourage retirement saving and healthcare planning.
These include employer-sponsored plans like the 401(k), individual accounts like the IRA, and medical savings vehicles like the HSA.
Understanding how these accounts interact allows you to build a resilient financial foundation.
This guide explains the mechanics, tax timing, contribution rules, and allocation order for each major vehicle.
Quick Summary
- Taxes significantly erode long-term compound growth when investments remain in standard taxable accounts.
- Tax-advantaged vehicles alter when taxes are assessed: upon contribution, during growth, or at withdrawal.
- Optimizing these accounts requires understanding the distinct roles of 401(k)s, IRAs, and HSAs.
The Friction of Tax Drag: Why Account Structure Matters
In a standard, taxable brokerage account, tax liabilities occur continually.
You purchase investments using income that has already been subject to federal, state, and local taxes.
When an asset pays a dividend, that dividend is taxed in the year it is received.
When you rebalance your portfolio by selling an asset, realized capital gains trigger immediate tax liabilities.
This ongoing taxation creates what financial analysts call tax drag.
Tax drag functions like constant resistance against your compounding returns.
To illustrate, imagine investing $10,000 annually over thirty years with an average nominal return of eight percent.
In a completely tax-sheltered environment, that portfolio grows to approximately $1.13 million.
In a taxable account subject to annual dividend drag and short- or long-term capital gains taxes, the final balance might drop to $800,000.
The difference of over $300,000 does not stem from poor asset selection.
It is lost purely to the mechanical inefficiency of tax timing.
Tax-advantaged accounts solve this problem by creating legal shelters around your assets.
Inside these shelters, dividends can be automatically reinvested without triggering current-year tax events.
Assets can be bought and sold within the account without generating taxable capital gains.
The timing of taxation is moved either to the initial contribution phase or the final withdrawal phase.
The Three Tax Pillars: Pre-Tax, Roth, and Tax-Free
Every tax-advantaged account operates under one of three fundamental tax structures.
Understanding these three models allows you to categorize any financial vehicle instantly.
1. Tax-Deferred (Traditional / Pre-Tax)
Contributions are made using pre-tax dollars, often deducted directly from your payroll.
This reduces your Adjusted Gross Income (AGI) for the current tax year.
Inside the account, assets grow completely shielded from annual dividend and capital gains taxes.
When you withdraw funds during retirement, every dollar withdrawn is taxed as ordinary income.
2. Tax-Exempt (Roth / Post-Tax)
Contributions are made using post-tax dollars, meaning you receive no upfront tax deduction.
Growth inside the account remains completely insulated from taxation.
When you take qualified withdrawals in retirement, the funds—including all accumulated capital gains—are entirely tax-free.
3. Triple Tax-Advantaged (Health Savings Account)
Contributions are pre-tax or tax-deductible, reducing your current-year taxable income.
Growth inside the account occurs tax-free without annual drag.
Withdrawals used for qualified medical expenses are completely tax-free at any age.
Key Takeaways
- Tax-deferred accounts trade upfront tax tax deductions for taxed withdrawals in retirement.
- Roth accounts trade current-year tax breaks for completely tax-free distributions in the future.
- Health Savings Accounts offer a rare triple tax advantage when funds are used for qualified medical expenses.
The Employer-Sponsored Giant: The 401(k) and 403(b)
The 401(k) is an employer-sponsored plan that serves as the primary retirement vehicle for millions of private-sector workers.
For employees in non-profit institutions, public schools, or government bodies, the equivalent vehicle is the 403(b) or 457(b) plan.
These accounts offer high annual contribution limits compared to individual accounts.
They also provide direct payroll integration, automating the habit of investing before income reaches your checking account.
Employer Match Dynamics: The Guaranteed Return
Many organizations offer an employer matching contribution to encourage participation.
A typical match formula might be 50 percent of employee contributions up to six percent of salary.
Alternatively, an employer might match 100 percent of contributions up to four percent of eligible earnings.
An employer match represents an immediate, risk-free return on your allocated dollars.
If an employer matches 100 percent up to four percent, depositing $1,000 yields an instant $1,000 addition to your account.
No market instrument or trading strategy offers a guaranteed 100 percent instant return.
For this reason, capturing the full employer match is almost universally considered the baseline first step in financial planning.
Traditional vs. Roth 401(k) Options
Many modern 401(k) plans now offer both Traditional and Roth options inside the same plan structure.
With a Traditional 401(k), your contributions lower your current taxable income.
With a Roth 401(k), you contribute post-tax dollars, but future withdrawals in retirement are tax-free.
Under current rules updated by SECURE Act 2.0 legislation, employer matching contributions can also be designated as Roth matching funds if the plan permits.
Contribution Limits and Catch-Up Provisions
The Internal Revenue Service (IRS) sets annual contribution limits for 401(k) accounts.
These limits are periodically adjusted for inflation.
Individual employee deferral limits apply to your own contributions across all 401(k) and 403(b) plans combined in a calendar year.
A separate total limit exists for combined employee and employer contributions.
Workers aged 50 and older are permitted to make additional catch-up contributions above the standard baseline.
| 401(k) Parameter | Standard Rule / Mechanics |
|---|---|
| Primary Benefit | High annual contribution cap and potential employer match |
| Tax Reduction Type | Choice of upfront tax deduction (Traditional) or tax-free distributions (Roth) |
| Access Rules | Penalty-free access generally begins at age 59½ |
| Early Withdrawal Penalty | 10% federal penalty plus ordinary income tax (with specific exceptions) |
The Individual Advantage: Traditional and Roth IRAs
An Individual Retirement Account (IRA) exists independently of your employer.
You can open an IRA at nearly any major investment brokerage platform.
This independence grants you complete control over your choice of investment instruments.
While 401(k) plans often restrict you to a curated menu of mutual funds, IRAs permit investment in broad-market index funds, ETFs, individual equities, and fixed-income assets.
Traditional IRA Mechanics and Income Limits
A Traditional IRA allows eligible individuals to contribute pre-tax or deductible dollars.
However, tax deductibility is subject to strict income limits if you or your spouse are covered by a workplace retirement plan.
If your Modified Adjusted Gross Income (MAGI) exceeds IRS thresholds, your ability to deduct Traditional IRA contributions phases out entirely.
You may still make non-deductible contributions to a Traditional IRA, but the upfront tax reduction is lost.
Roth IRA Mechanics and Eligibility Rules
A Roth IRA allows post-tax contributions that grow completely tax-free.
Qualified distributions taken after age 59½ and after meeting the five-year account age rule are entirely free of federal income tax.
Roth IRAs also feature unique flexibility regarding early access to capital.
Because you contributed post-tax dollars, you can withdraw your original principal contributions at any time, for any reason, without taxes or penalties.
However, investment earnings generated inside the Roth IRA must remain in the account until qualified retirement age to avoid penalties.
Direct Roth IRA eligibility is restricted by income.
When MAGI reaches specified phase-out ranges, maximum contribution limits are reduced, eventual hitting zero for higher earners.
The Backdoor Roth IRA Mechanism
High earners who are barred from direct Roth IRA contributions due to income limits often utilize a strategy known as the Backdoor Roth IRA.
This two-step mechanical process involves making a non-deductible contribution to a Traditional IRA, followed by a tax-free conversion of those funds into a Roth IRA.
Because there are no income limits on non-deductible Traditional IRA contributions or Roth conversions, this opens the Roth structure to higher earners.
However, this strategy requires careful handling of the IRS Pro-Rata Rule if you hold pre-tax balances in any Traditional, SEP, or SIMPLE IRAs.
In Short
- IRAs provide expanded investment choices compared to employer plans.
- Traditional IRA tax deductions phase out at higher income tiers if covered by a workplace plan.
- Roth IRAs permit penalty-free withdrawal of original contribution principal at any time.
The Health Savings Account (HSA): Stealth Retirement Vehicle
The Health Savings Account was created to help individuals save for medical costs under high-deductible health insurance plans.
However, its structural tax characteristics make it one of the most powerful wealth accumulation vehicles available.
The HSA is unique because it offers three distinct tax advantages in a single account.
The Triple Tax Advantage Explained
First, contributions are made on a pre-tax basis, reducing your current income tax liability.
If contributed through payroll deduction, contributions also bypass Social Security and Medicare taxes (FICA taxes), saving an additional 7.65 percent.
Second, funds inside the account can be invested in broad-market index funds and grow completely tax-free.
Third, withdrawals used to reimburse qualified medical expenses are completely tax-free at any time.
HSA Eligibility Requirements
To qualify for HSA contributions, you must be covered under a qualifying High Deductible Health Plan (HDHP).
An HDHP features higher annual deductibles than traditional PPO plans, but lower monthly premiums.
You cannot be enrolled in Medicare, nor can you be claimed as a dependent on another individual’s tax return.
The Long-Term ‘Shoebox’ Strategy
Many investors treat the HSA as a standard medical checking account, using funds immediately when doctor bills arrive.
While practical, this strategy misses the long-term compounding potential of the vehicle.
A more growth-oriented approach involves paying out-of-pocket medical costs using standard cash flow from income.
Meanwhile, you leave your HSA balance fully invested in broad-market equity index funds.
You save every receipt for qualifying medical expenses incurred after the account was opened in a secure digital file.
Under current tax laws, there is no deadline for when you must reimburse yourself for an eligible medical expense.
You can incur a $2,000 medical cost today, let that $2,000 remain invested in your HSA for twenty years, and then tax-freely reimburse yourself decades later.
At age 65, HSA rules relax further.
After age 65, you can withdraw funds for non-medical expenses without paying a penalty.
The distribution will simply be taxed as ordinary income, making it function identically to a Traditional 401(k) or Traditional IRA for non-medical expenses, while maintaining tax-free status for medical costs.
Side-by-Side Account Comparison Matrix
Choosing where to direct your next savings dollar requires clear structural comparison.
The following comparison table breaks down the core parameters across 401(k), IRA, and HSA structures.
| Feature / Rule | 401(k) / 403(b) | Traditional / Roth IRA | Health Savings Account (HSA) |
|---|---|---|---|
| Primary Requirement | Employer sponsorship | Earned income | HDHP coverage requirement |
| Upfront Tax Benefit | Pre-tax deferral available | Deductible (income limited) | Pre-tax deferral + FICA exemption |
| Growth Phase | Tax-sheltered | Tax-sheltered | Tax-sheltered |
| Withdrawal Tax | Taxed (Trad) / Free (Roth) | Taxed (Trad) / Free (Roth) | Free for medical expenses |
| Investment Control | Curated plan lineup | Full open market selection | Varies by administrator |
| Penalty Age | Under age 59½ (generally) | Under age 59½ (contributions exempt in Roth) | Under age 65 for non-medical |
The Optimal Funding Waterfall: Where to Put Money First
When you have savings available, allocating capital randomly across accounts reduces overall efficiency.
Financial planners use an ordering framework known as a funding waterfall.
This framework directs every dollar to its highest mathematical leverage before moving to the next tier.
Step 1: Capture the Full Employer 401(k) Match
Never leave employer matching funds uncaptured.
Contribute enough to your workplace 401(k) or 403(b) to secure every matching dollar offered by your firm.
This provides an immediate, guaranteed return that cannot be equaled by other asset classes.
Step 2: Eliminate High-Interest Consumer Debt
Before funding non-matched investment accounts, eliminate high-interest debt like credit cards or high-rate personal loans.
Paying off a debt carrying a sixteen percent interest rate provides a guaranteed rate of return equal to sixteen percent after tax.
Step 3: Maximize Health Savings Account (HSA)
If you are covered under an eligible High Deductible Health Plan, fund your HSA next.
The combination of pre-tax savings, FICA tax reduction, tax-free growth, and tax-free qualified withdrawals gives the HSA priority over standard retirement accounts.
Step 4: Maximize Individual Retirement Accounts (Roth or Traditional IRA)
Once your HSA is fully funded, direct capital to an IRA.
If your income permits direct contributions or if you utilize a Backdoor Roth strategy, a Roth IRA offers superior withdrawal flexibility and tax diversification in retirement.
If you qualify for a full tax deduction on a Traditional IRA and anticipate being in a lower marginal bracket during retirement, a Traditional IRA may be preferred.
Step 5: Return to Fill Remaining Workplace Plan Limits
If you still have available investment capital, direct funds back into your 401(k) or 403(b) until you hit the maximum annual limit.
Step 6: Utilize Taxable Brokerage Accounts
Once all tax-advantaged account options are fully exhausted, direct excess long-term capital toward a standard taxable brokerage account.
Focus taxable account investments on tax-efficient asset classes, such as low-turnover, broad-market equity index ETFs.
Bottom Line
- Prioritize employer-matched accounts first to secure guaranteed match funds.
- Fund triple-advantaged HSAs and flexible IRAs before filling unmatched 401(k) capacity.
- Reserve taxable brokerage accounts for capital that exceeds all annual tax-sheltered limits.
Step-by-Step Execution Guide: Setting Up Your Account Architecture
Building a tax-efficient system requires practical, step-by-step account configuration.
Follow this checklist to audit and optimize your current account architecture.
- Audit your workplace plan options: Log into your company payroll or benefit portal. Confirm your current contribution percentage and review the exact match threshold offered by your employer.
- Verify matching contributions: Ensure your contribution percentage meets or exceeds the minimum required to capture the full company match.
- Check HDHP eligibility: Review your health insurance plan details. Confirm whether your deductible and out-of-pocket maximums qualify you for an HSA.
- Select an IRA provider: Open a Traditional or Roth IRA with a reputable discount brokerage offering zero commission rates and broad index fund availability.
- Establish automated contributions: Configure recurring transfers timed to match your paydays. Automated deposits ensure disciplined execution without relying on manual decisions.
- Select low-cost core holdings: Invest account balances in low-cost, broad-market index funds or total market ETFs to minimize internal expense ratios.
- Schedule an annual review: Review IRS contribution adjustments each year in November or December to update your automated monthly allocations.
Common Tax Traps and Mistakes to Avoid
Tax-advantaged accounts carry strict rules set by the tax code.
Making mechanical errors can trigger unwanted penalties, taxes, or loss of compounding potential.
1. Leaving Account Balances in Uninvested Cash
Opening an IRA or HSA is only the first part of the process.
Funds deposited into these accounts sit in a cash settlement account until you explicitly choose investment assets.
Thousands of savers discover years later that their contributions sat idle in cash, completely missing market growth.
2. Triggering the Pro-Rata Rule on Roth Conversions
If you execute a Backdoor Roth IRA conversion while holding pre-tax balances in any Traditional IRA, the IRS applies the Pro-Rata Rule.
The IRS looks at all your Traditional IRA assets collectively rather than isolating the non-deductible contribution.
This causes a portion of your conversion to be taxed as ordinary income, frustrating high-earning investors who assumed the move would be entirely non-taxable.
3. Ignoring Required Minimum Distributions (RMDs)
Traditional 401(k) and Traditional IRA structures require you to begin taking annual distributions once you reach a specific age, as defined under updated SECURE Act rules.
Failing to take a required distribution results in substantial excise tax penalties imposed by the IRS on the unwithdrawn amount.
Roth IRAs do not require minimum distributions during the original account holder’s lifetime.
4. Premature Liquidation and Penalty Costs
Liquidating retirement accounts early to pay for lifestyle expenses or discretionary purchases incurs a heavy financial loss.
In addition to ordinary income taxes, early withdrawals generally incur a 10 percent IRS early withdrawal penalty.
More importantly, you permanently destroy tax-sheltered growth capacity that can never be bought back.
Conclusion: Financial Education and Personalized Decision Support
Tax-advantaged accounts are powerful instruments designed to protect long-term capital from tax friction.
By understanding how tax-deferred, tax-exempt, and triple tax-advantaged accounts operate, you can make clear, informed choices suited to your unique timeline.
Remember that tax rules, contribution limits, and personal income brackets shift over time.
Treat this framework as ongoing financial education and decision support.
For personalized guidance regarding complex tax situations or individual asset strategies, consult a qualified, fee-only financial planner or a certified public accountant.